


If Your Contractor Only Looked at Your Roof After a Chicagoland Hail Storm, You Left Money on the Table
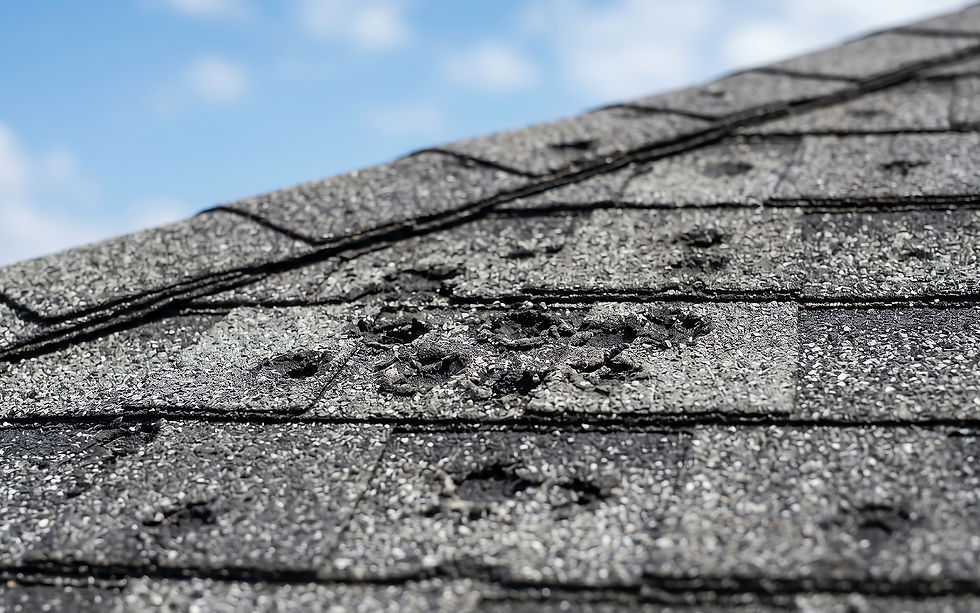
If the estimate for your hail damage roof repair stopped at the roofline, there's a good chance your insurance claim did too. Chicagoland hailstorms don't stop at the home’s roof and shingles. They move straight into the siding, gutters, and window trim on the same side of the house, and if your contractor never inspected those systems, that damage never made it into your claim. Here's what a roof-only inspection typically leaves out, and what you can still do about it.
Why One Hailstorm Damages More Than Your Roof
Hail doesn't select which building material it hits. A hailstone traveling at speed strikes whatever surface is in its path, whether that's a roof shingle, a siding panel, a gutter run, or a window screen a few feet away. The angle and velocity that bruise your shingles are the same angle and velocity striking your siding and trim during the exact same event. There's no such thing as a hailstorm that damages only the roof and leaves the rest of the exterior untouched.
The Exterior Systems Hail Puts at Risk
A full hail inspection covers every exterior surface exposed during the storm, not just the field of the roof. Three systems in particular carry damage that's easy for a roof-only inspection to miss entirely.
Siding Bruising and Cracking
Vinyl and fiber cement siding bruises and cracks under hail impact the same way shingles do, and insurance carriers recognize hail damage siding repair as a covered loss when it's documented. The damage often shows up as small circular impact marks, hairline cracks along panel seams, or chalking where the surface coating has been knocked loose. Because siding damage rarely looks as dramatic as a torn-up roof, it's the system most often left off a hasty inspection. A full accounting of the siding needs to happen at the same time as the roof, not as an afterthought weeks later.
Gutter Denting and Drainage Damage
Gutters take a direct hit during any hailstorm large enough to damage a roof, and the dents that result aren't just cosmetic. Denting changes the pitch of a gutter run enough to disrupt drainage, which sends water toward the foundation and fascia instead of away from the house. A gutter system that's compromised after a storm needs the same documentation as the roof itself, since drainage failure causes damage that compounds for months after the storm has passed. That connection is often missing from a roof-only inspection report.
Soffit, Fascia, and Window Damage
Soffit and fascia sit directly under the roofline and take hail impact at a steep angle, which means damage here is easy to miss from the ground and even easier to miss from a roof-focused inspection. Window damage tends to hit hardest on the side of the house that faced the storm, showing up as cracked screens, dented frames, or compromised glazing seals. Both are exterior systems with their own coverage under most homeowner policies, and both require someone who's actually looking for them. A window and door inspection covers this ground, but only if it's part of the original scope.
Why a Roofing-Only Contractor Misses the Rest of the Claim
The gap isn't usually about competence. It comes down to scope and incentive.
Different Trades, Different Scopes
Most roofing contractors are scoped, priced, and paid for one job: the roof. Siding, gutter, and window damage falls to separate trade contractors, and a roofer who isn't licensed or equipped for those systems has little reason to document damage he isn't going to repair. That's not a failure of the contractor you hired. It's a structural gap in how most storm response work gets divided up.
What a Full-Exterior Inspection Catches
A contractor who inspects the entire exterior, not just the roof, documents siding, gutters, soffit, fascia, and windows as part of the same visit and the same claim. That single inspection becomes the foundation for a complete insurance submission instead of a partial one, and it's the difference between recovering what your policy actually covers and leaving money with the insurance company. Working with a team that documents the full exterior scope from the start means nothing gets discovered after the settlement check has already cleared.
What an Incomplete Claim Actually Costs You
Missing systems on a claim isn't a paperwork problem. It's money that stays with the insurance company instead of paying for repairs you're entitled to.
Siding Losses Add Up Fast
Siding replacement on a Chicagoland home is a claimable loss that routinely runs into five figures once an entire elevation needs to be matched and replaced. When a roof storm damage repair claim closes without a siding inspection, that entire line item simply never gets submitted. Insurance doesn't pay for damage nobody documented, no matter how real it is.
Gutters and Fascia Compound the Loss
Gutters and fascia add thousands more when they're included in the original claim instead of discovered later as a separate, harder-to-justify request. Filing a supplemental claim after settlement is possible, but it's a heavier lift than including everything the first time. The homeowners who recover the most are the ones whose contractor looked at every system before the claim was ever submitted.
What a Free Re-Inspection From Semper Fi Covers
Whether your claim has already settled or you haven't called anyone yet this storm season, a full exterior re-inspection starts the same way. Homeowners who are still deciding who to hire can build the full-system approach into their very first inspection instead of correcting for it later, avoiding the entire problem this article addresses in the first place.
A Full Exterior Walkthrough
Semper Fi Construction inspects the roof, siding, gutters, soffit, fascia, and windows in the same visit, whether that's your first hail damage roof repair inspection this season or a second look at a claim that's already closed. Every finding is documented with photos and a written report that's ready to support a new claim or a supplemental request on an existing one. If your roof already went through a storm damage roof replacement and nothing else was checked, this is the visit that closes that gap.
Serving Homeowners Across Chicagoland
This coverage extends across DuPage, Cook, Kane, Will, and Kendall Counties, including Naperville, Bolingbrook, Downers Grove, Westmont, Darien, Lombard, and Joliet. Homeowners throughout the full Chicagoland service area get the same licensed, bonded, and insured team and the same full-exterior standard, regardless of which contractor handled the original work.
Get a Second Look Before Your Hail Damage Roof Repair Claim Closes
A roof-only inspection usually isn't wrong. It's just incomplete, and incomplete is what costs Chicagoland homeowners real money after every hail season. The systems most often left off a claim- siding, gutters, soffit, fascia, and windows- are just as damaged and just as covered as the roof itself. Whether your claim already closed or storm season is still moving through DuPage and Cook Counties, the window to get this right hasn't necessarily shut.
Semper Fi Construction is a hail damage roofing company built around the full exterior, not just the shingles, and every re-inspection comes with the same licensed, bonded, and insured standard the company applies to every roof replacement it completes. If you're wondering whether your last inspection told you the whole story, reach out and let's find out together.


Comments